Exhibit 99.2
| Global. Connected. Sustainable. 3Q26 FINANCIAL RESULTS October 29, 2026 The meeting place for companies, technologies and data |
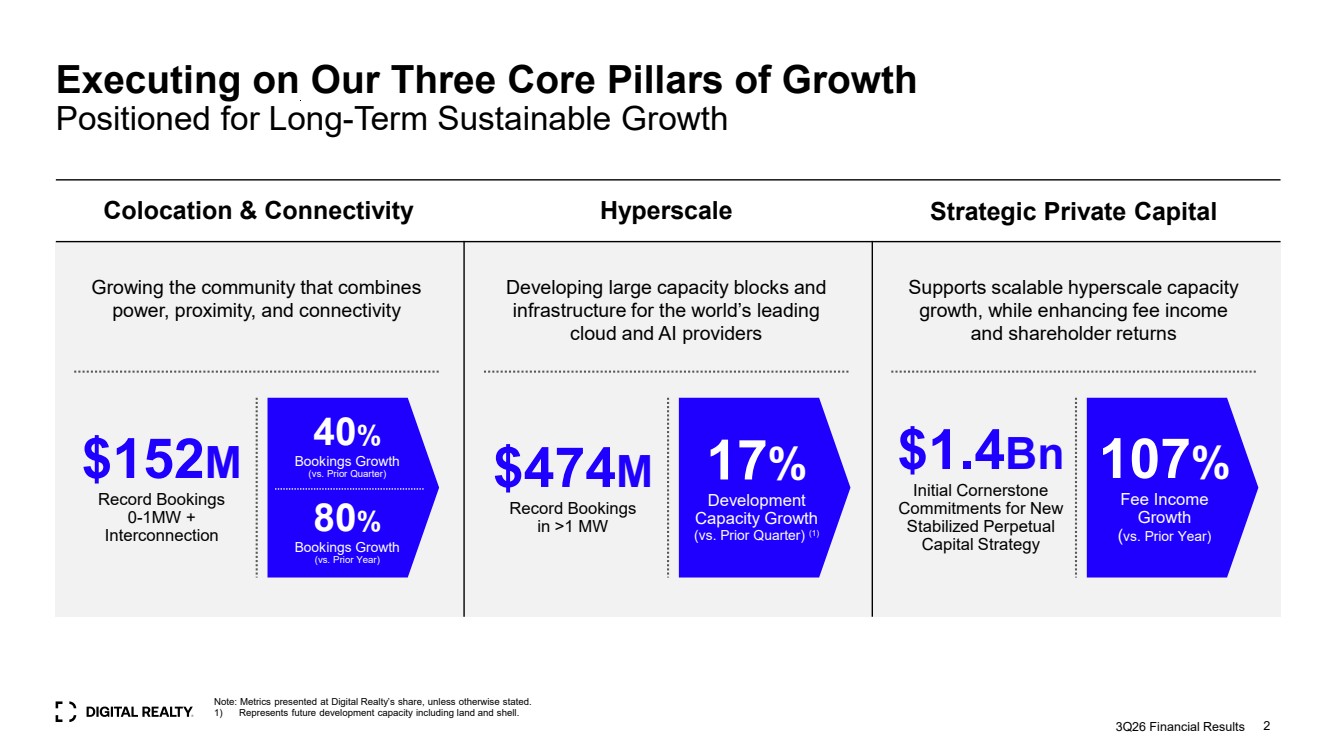
| Growing the community that combines power, proximity, and connectivity $152M Record Bookings 0-1MW + Interconnection Developing large capacity blocks and infrastructure for the world’s leading cloud and AI providers Supports scalable hyperscale capacity growth, while enhancing fee income and shareholder returns Colocation & Connectivity Hyperscale Strategic Private Capital 3Q26 Financial Results 2 Executing on Our Three Core Pillars of Growth Positioned for Long-Term Sustainable Growth $474M Record Bookings in >1 MW 17% Development Capacity Growth (vs. Prior Quarter) (1) $1.4Bn Initial Cornerstone Commitments for New Stabilized Perpetual Capital Strategy 107% Fee Income Growth (vs. Prior Year) Note: Metrics presented at Digital Realty’s share, unless otherwise stated. 1) Represents future development capacity including land and shell. 40% Bookings Growth (vs. Prior Quarter) 80% Bookings Growth (vs. Prior Year) |
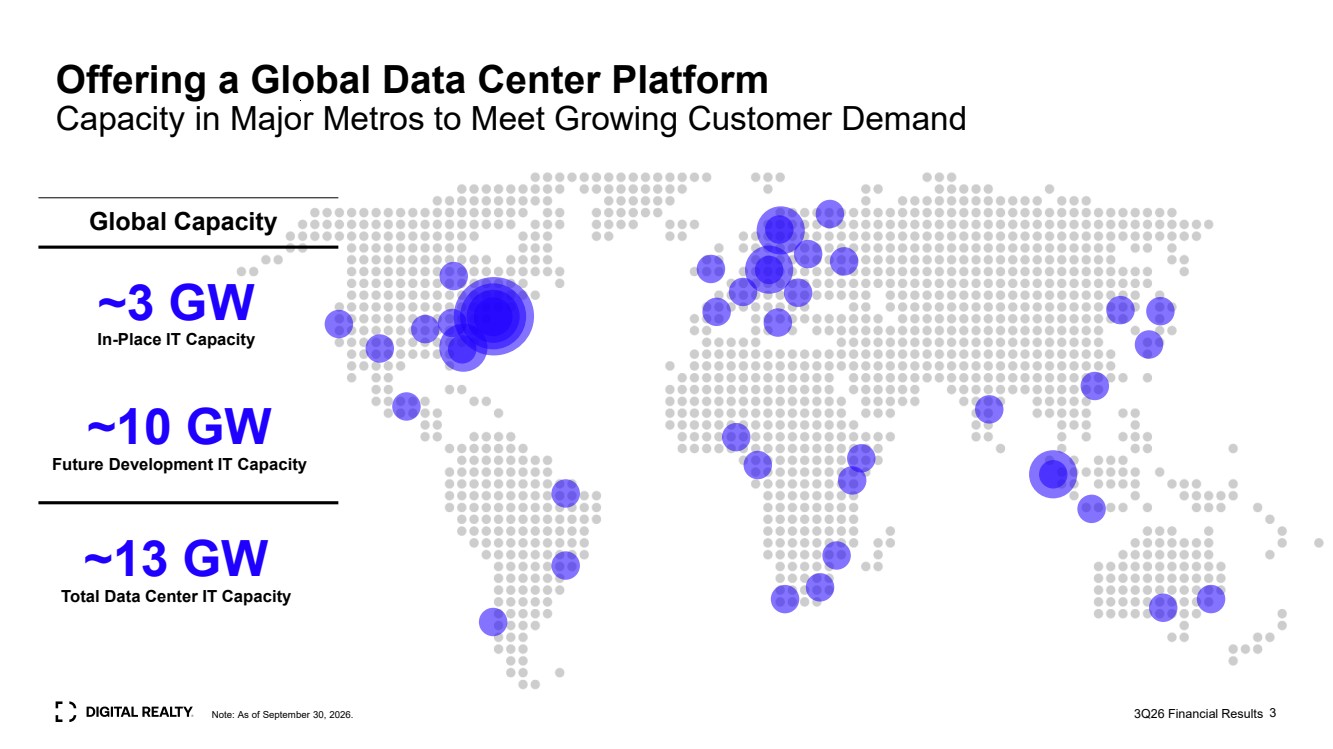
| 3 Offering a Global Data Center Platform Capacity in Major Metros to Meet Growing Customer Demand Global Capacity ~10 GW Future Development IT Capacity 3Q26 Financial Results ~3 GW In-Place IT Capacity Note: As of September 30, 2026. ~13 GW Total Data Center IT Capacity |
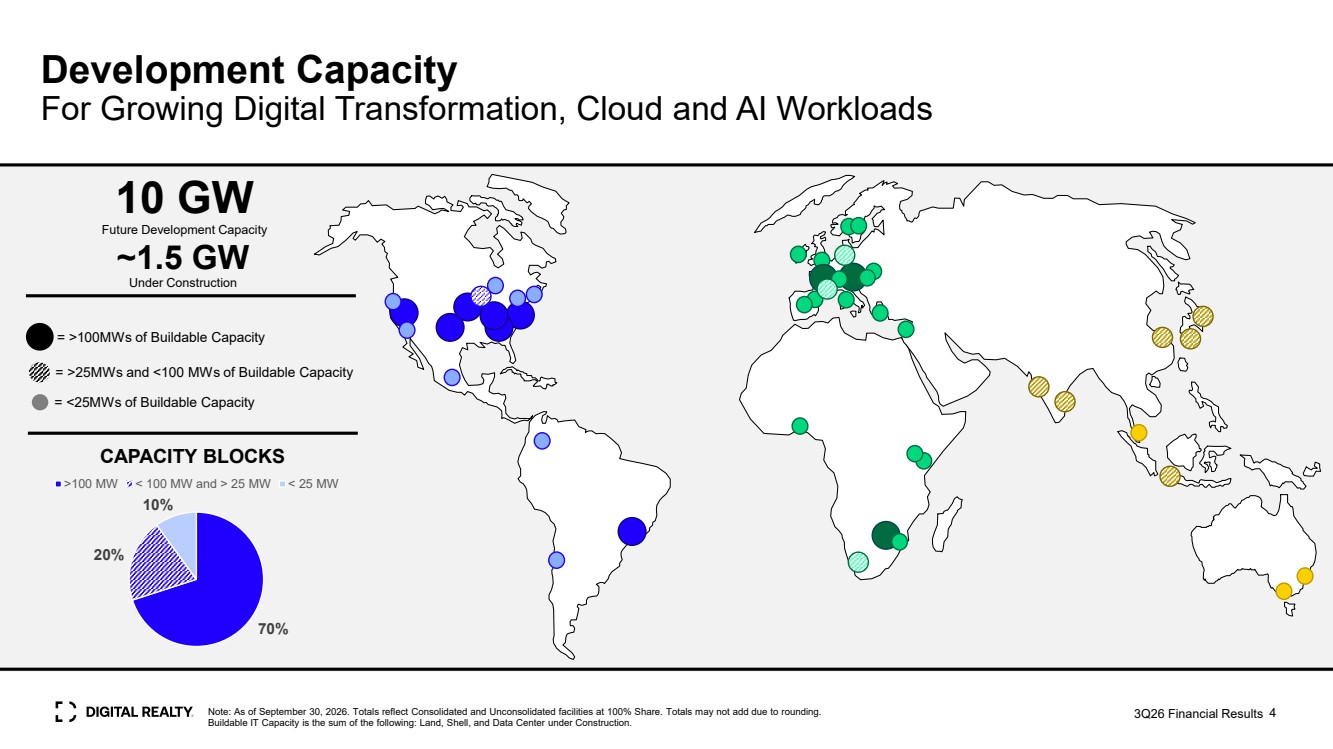
| Note: As of September 30, 2026. Totals reflect Consolidated and Unconsolidated facilities at 100% Share. Totals may not add due to rounding. Buildable IT Capacity is the sum of the following: Land, Shell, and Data Center under Construction. 4 >5 GW Future Development Capacity = >25MWs and <100 MWs of Buildable Capacity = <25MWs of Buildable Capacity = >100MWs of Buildable Capacity Development Capacity For Growing Digital Transformation, Cloud and AI Workloads Future 10 G Development Capacity W 70% 20% 10% >100 MW < 100 MW and > 25 MW < 25 MW CAPACITY BLOCKS 3Q26 Financial Results ~1.5 GW Under Construction |
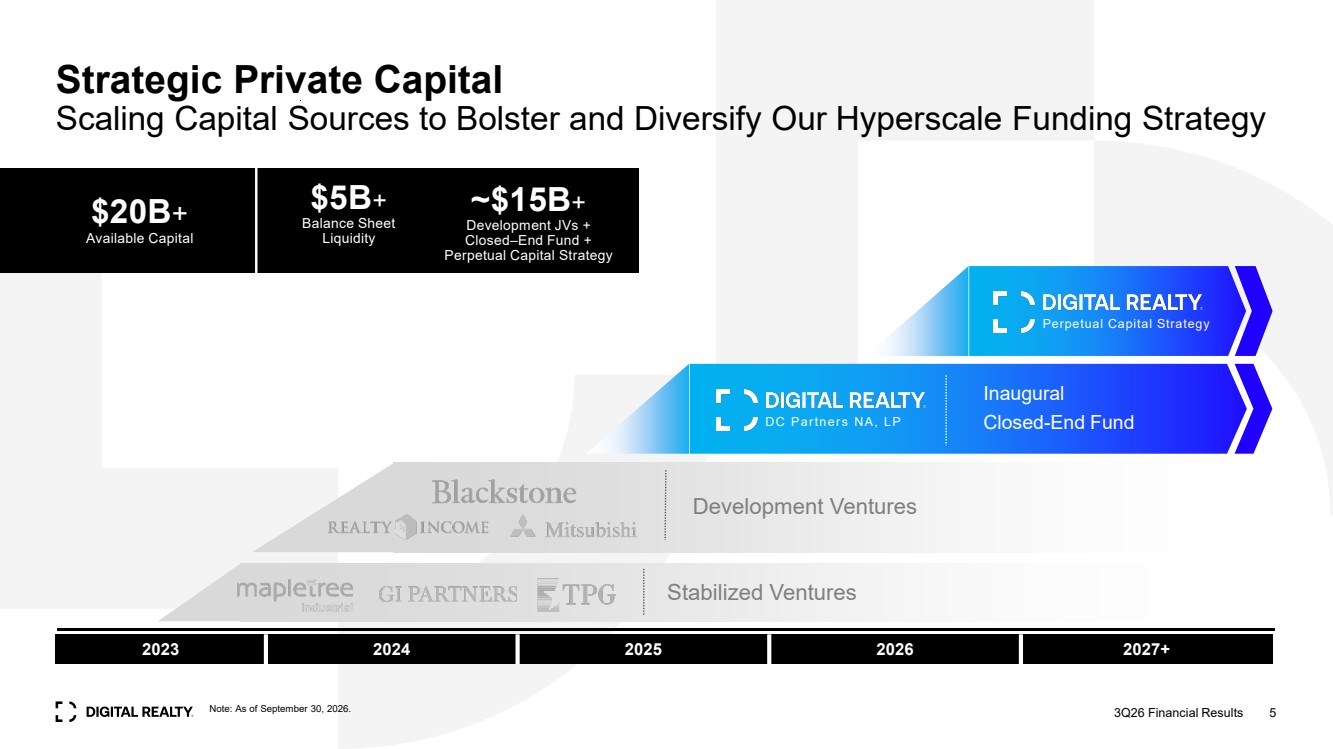
| 3Q26 Financial Results 5 Strategic Private Capital Scaling Capital Sources to Bolster and Diversify Our Hyperscale Funding Strategy 2023 2024 2025 2026 2027+ Stabilized Ventures Development Ventures Perpetual Capital Strategy DC Partners NA, LP Inaugural Closed-End Fund Note: As of September 30, 2026. $20B+ Available Capital ~$15B+ Development JVs + Closed–End Fund + Perpetual Capital Strategy $5B+ Balance Sheet Liquidity |
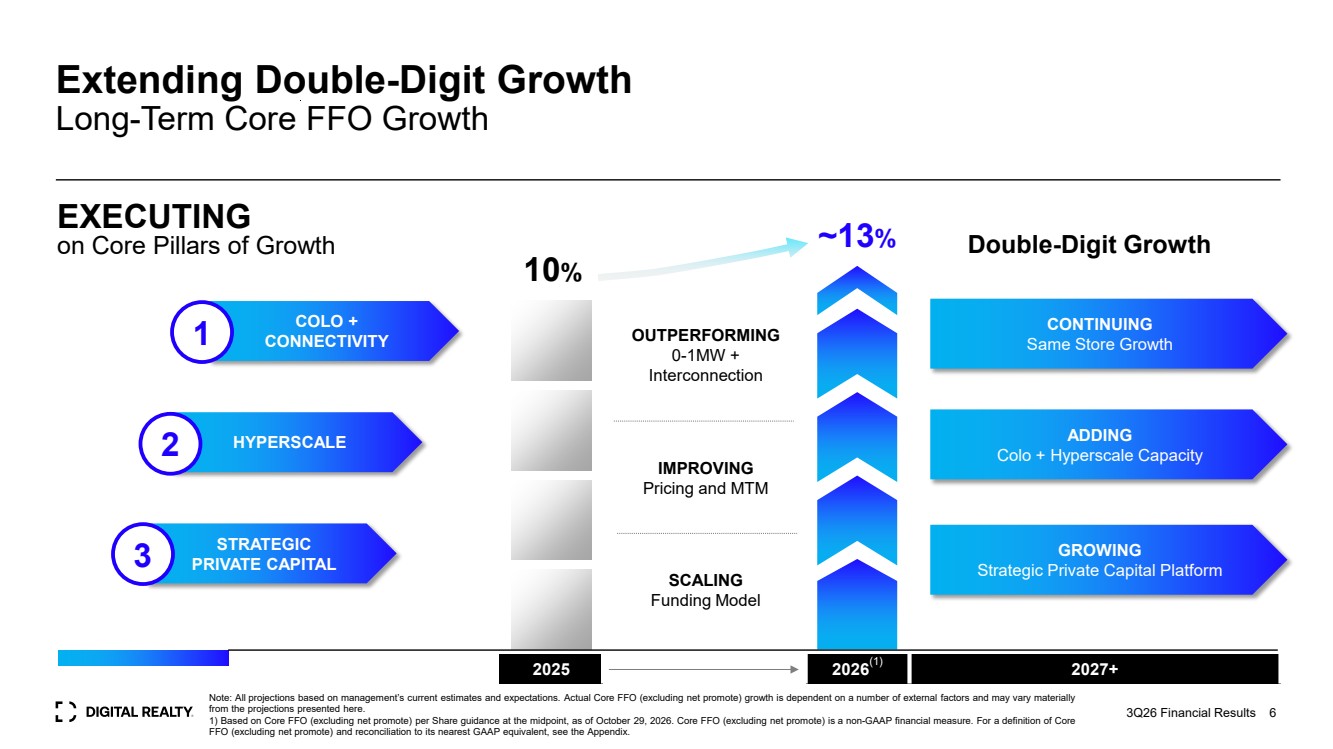
| 2025 2026(1) 2027+ 6 Note: All projections based on management’s current estimates and expectations. Actual Core FFO (excluding net promote) growth is dependent on a number of external factors and may vary materially from the projections presented here. 1) Based on Core FFO (excluding net promote) per Share guidance at the midpoint, as of October 29, 2026. Core FFO (excluding net promote) is a non-GAAP financial measure. For a definition of Core FFO (excluding net promote) and reconciliation to its nearest GAAP equivalent, see the Appendix. 3Q26 Financial Results Extending Double-Digit Growth Long-Term Core FFO Growth COLO + CONNECTIVITY EXECUTING on Core Pillars of Growth STRATEGIC PRIVATE CAPITAL HYPERSCALE 3 2 1 10% ~13% OUTPERFORMING 0-1MW + Interconnection SCALING Funding Model IMPROVING Pricing and MTM CONTINUING Same Store Growth GROWING Strategic Private Capital Platform ADDING Colo + Hyperscale Capacity Double-Digit Growth |
| 3Q26 Financial Results 3Q26 Financial Results 7 |
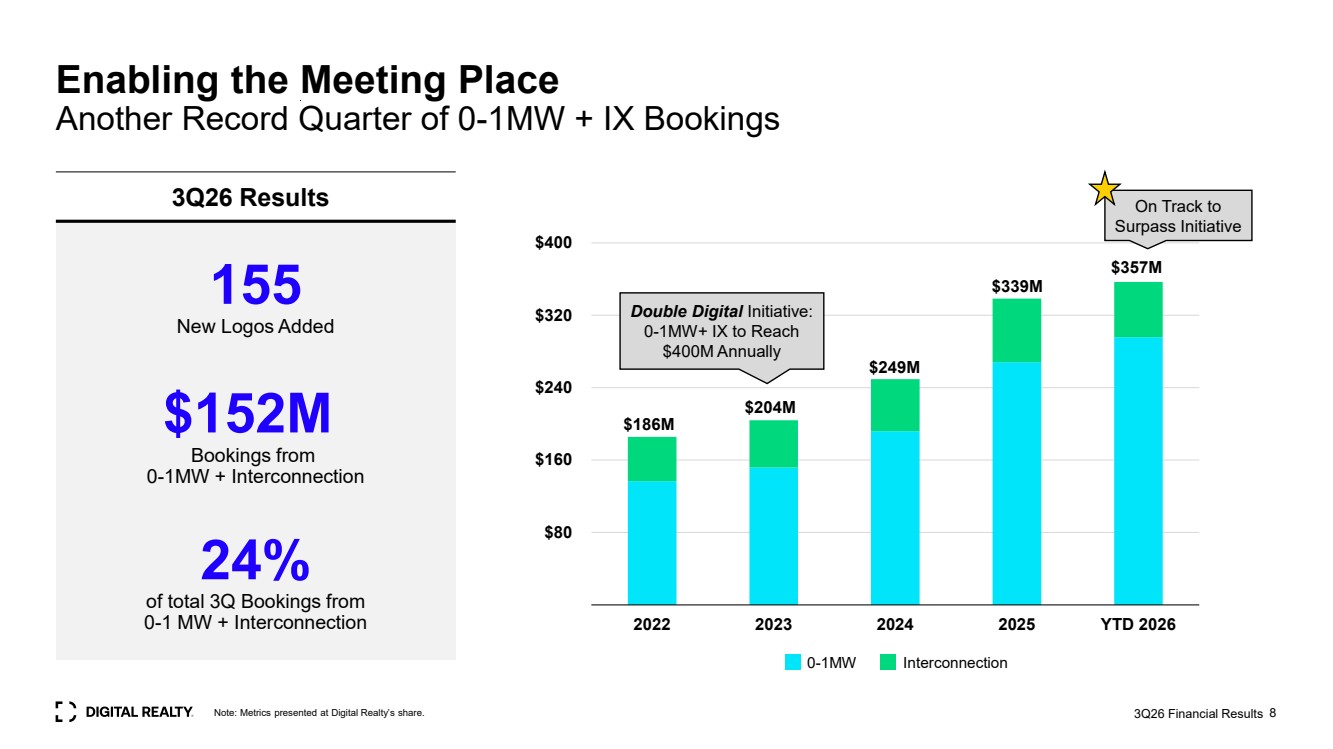
| 3Q26 Financial Results 8 Enabling the Meeting Place Another Record Quarter of 0-1MW + IX Bookings 155 New Logos Added $152M Bookings from 0-1MW + Interconnection 24% of total 3Q Bookings from 0-1 MW + Interconnection 3Q26 Results Note: Metrics presented at Digital Realty’s share. $80 $160 $240 $320 $400 2022 2023 2024 2025 YTD 2026 0-1MW Interconnection $186M $249M $339M $357M $204M Double Digital Initiative: 0-1MW+ IX to Reach $400M Annually On Track to Surpass Initiative |
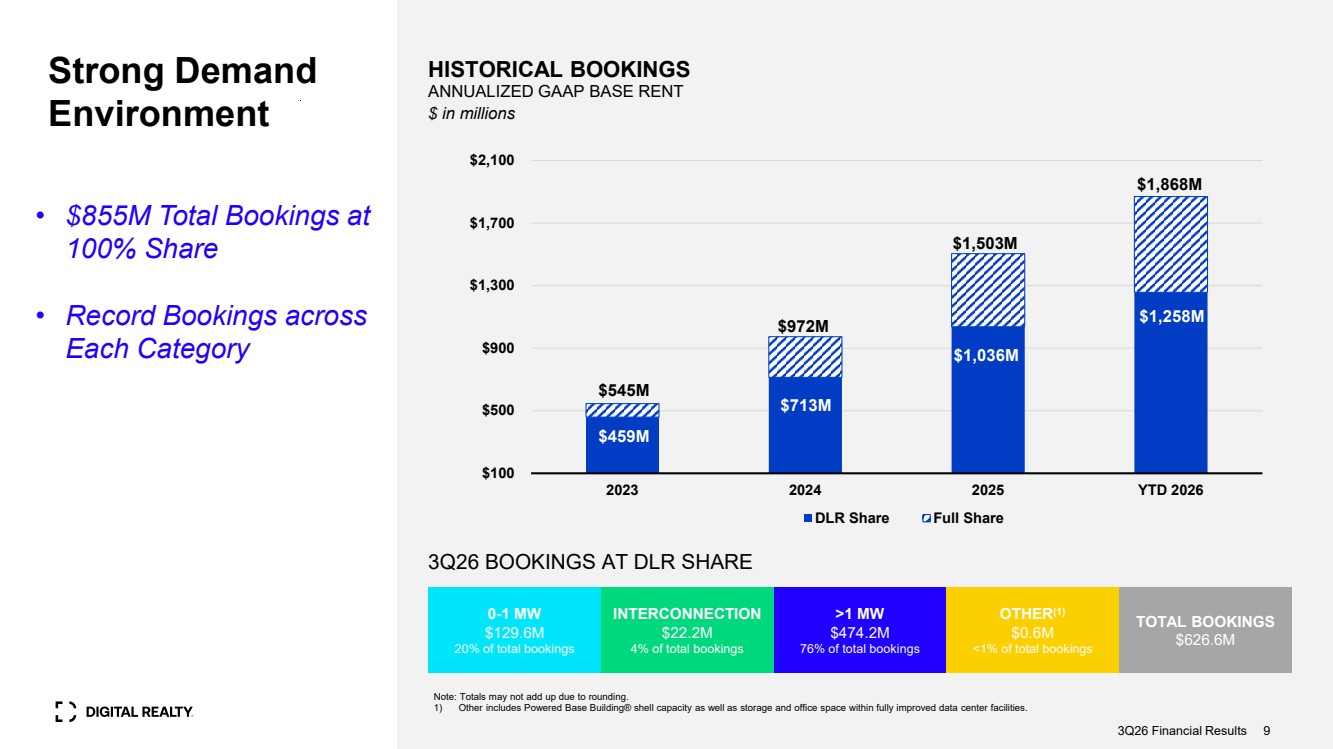
| Note: Totals may not add up due to rounding. 1) Other includes Powered Base Building® shell capacity as well as storage and office space within fully improved data center facilities. 3Q26 BOOKINGS AT DLR SHARE HISTORICAL BOOKINGS ANNUALIZED GAAP BASE RENT $ in millions Strong Demand Environment 0-1 MW $129.6M 20% of total bookings INTERCONNECTION $22.2M 4% of total bookings >1 MW $474.2M 76% of total bookings OTHER(1) $0.6M <1% of total bookings TOTAL BOOKINGS $626.6M 3Q26 Financial Results 9 • $855M Total Bookings at 100% Share • Record Bookings across Each Category $100 $500 $900 $1,300 $1,700 $2,100 2023 2024 2025 YTD 2026 DLR Share Full Share $545M $972M $1,503M $1,868M $459M $1,258M $1,036M $713M |
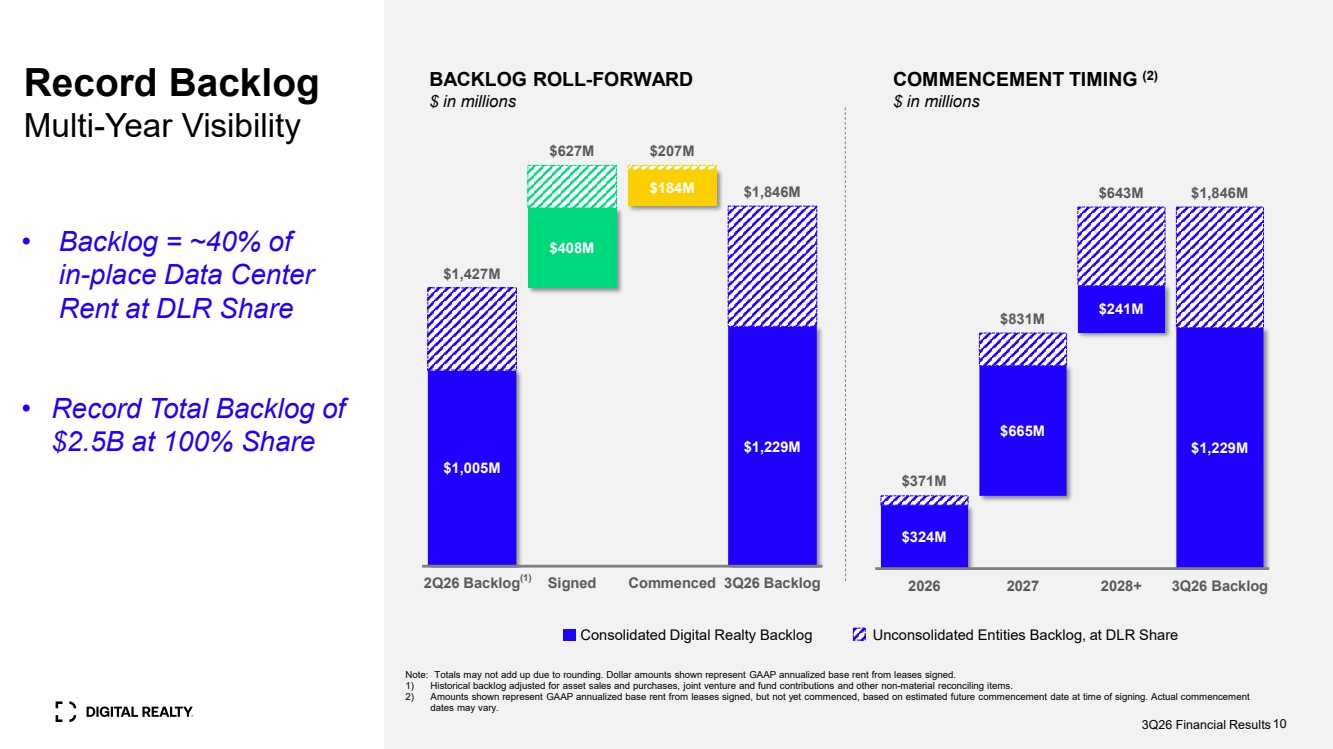
| Note: Totals may not add up due to rounding. Dollar amounts shown represent GAAP annualized base rent from leases signed. 1) Historical backlog adjusted for asset sales and purchases, joint venture and fund contributions and other non-material reconciling items. 2) Amounts shown represent GAAP annualized base rent from leases signed, but not yet commenced, based on estimated future commencement date at time of signing. Actual commencement dates may vary. BACKLOG ROLL-FORWARD $ in millions Consolidated Digital Realty Backlog Unconsolidated Entities Backlog, at DLR Share COMMENCEMENT TIMING (2) $ in millions 3Q26 Financial Results10 $1,005M $408M $184M $1,229M $1,427M $627M $207M $1,846M 2Q26 Backlog Signed Commenced 3Q26 Backlog (1) • Backlog = ~40% of in-place Data Center Rent at DLR Share • Record Total Backlog of $2.5B at 100% Share Record Backlog Multi-Year Visibility $324M $665M $241M $1,229M $371M $831M $643M $1,846M 2026 2027 2028+ 3Q26 Backlog |
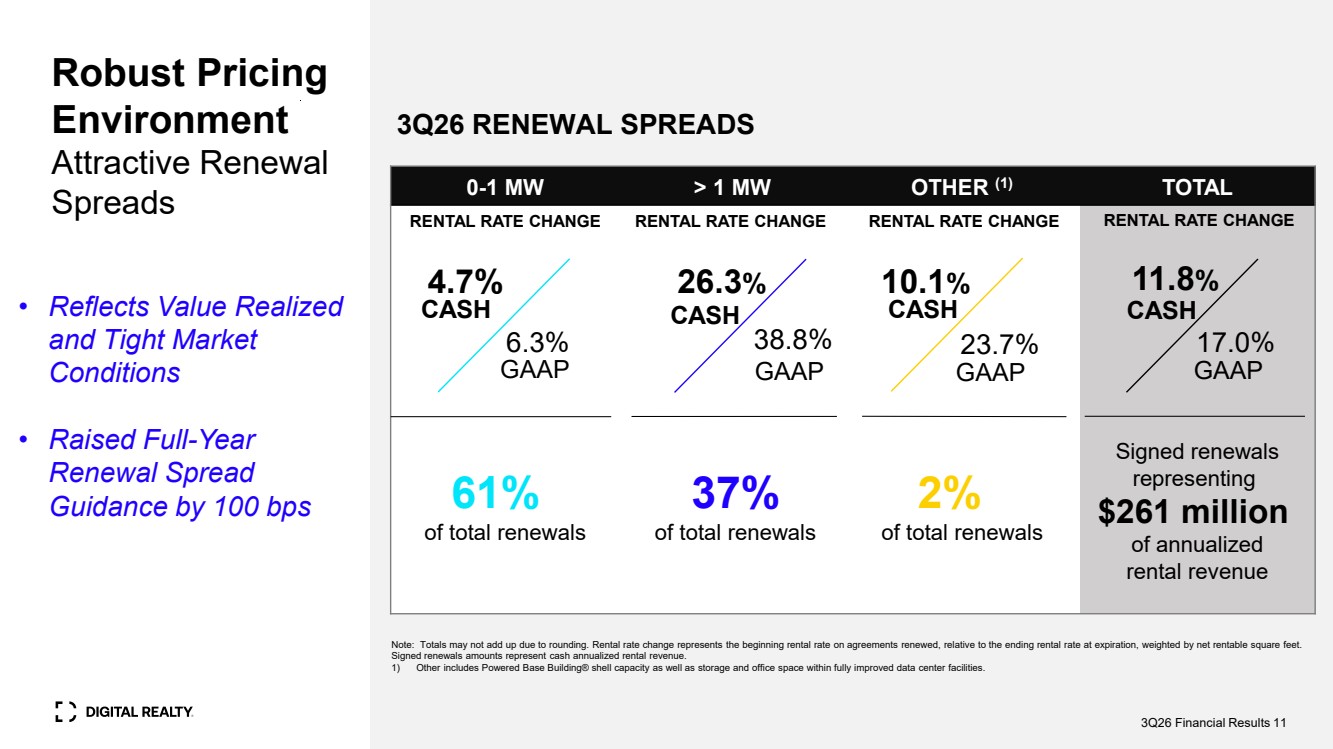
| Robust Pricing Environment Attractive Renewal Spreads 3Q26 RENEWAL SPREADS 0-1 MW > 1 MW OTHER (1) TOTAL 61% of total renewals 37% of total renewals 2% of total renewals Signed renewals representing $261 million of annualized rental revenue RENTAL RATE CHANGE RENTAL RATE CHANGE RENTAL RATE CHANGE RENTAL RATE CHANGE 6.3% 26.3% GAAP Note: Totals may not add up due to rounding. Rental rate change represents the beginning rental rate on agreements renewed, relative to the ending rental rate at expiration, weighted by net rentable square feet. Signed renewals amounts represent cash annualized rental revenue. 1) Other includes Powered Base Building® shell capacity as well as storage and office space within fully improved data center facilities. 4.7% CASH GAAP CASH 38.8% 10.1% CASH 23.7% GAAP 11.8% CASH 17.0% GAAP 3Q26 Financial Results 11 • Reflects Value Realized and Tight Market Conditions • Raised Full-Year Renewal Spread Guidance by 100 bps |
| Revenue Exposure by Currency Currency Tailwinds 1% 4% 22% 5% 56% <1% 2% 4% 2026E $8.325 / Sh 1% SOFR +/- 100bps +0% GBP +/- 10% 2% EUR +/- 10% CORE FFO (excluding net promote) /SHARE EXPOSURE (2) EXPOSURE BY REVENUE (1) Note: Totals may not add up due to rounding. 1) As of September 30, 2026. Includes Digital Realty’s share of revenue from unconsolidated entities. 2) Core FFO (excluding net promote) is a non-GAAP financial measure. For a definition of Core FFO (excluding net promote) and reconciliation to its nearest GAAP equivalent, see the Appendix. 3Q26 Financial Results 12 <1% • Local Operations Funded in Local Currencies Act as a Natural Hedge • Minimal FX Impact in 3Q <1% <1% 3Q25 U.S. DOLLAR INDEX 3Q26 ZAR 4% USD EURO SGD GBP 22% 5% 4% CHF 1% AUS 56% 2% 1% JPY CAD 2% <1% <1% <1% 2% Oct-26 <1% 1% <1% <1% <1% OTHER 85 90 95 100 105 110 Jul-25 Oct-25 Jan-26 Apr-26 Jul-26 <1% <1% <1% |
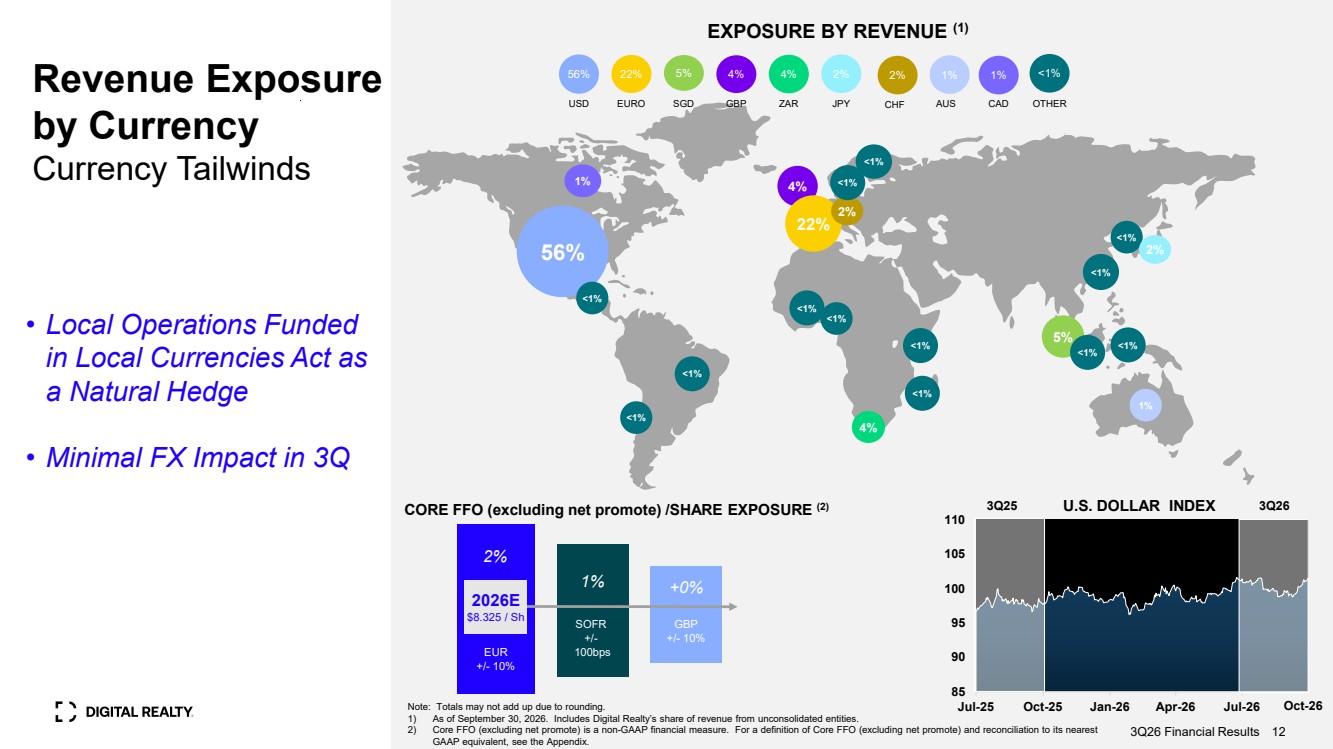
| Strengthening the Balance Sheet While Funding Growth 4.9x Pro Forma Leverage $20B Capital Available to Support Future Development NET DEBT TO ADJUSTED EBTIDA(1) 3Q26 Financial Results Note: 1) Net Debt to Adjusted EBITDA is calculated as total debt at balance sheet carrying value (see Appendix), plus capital lease obligations, plus our share of Joint Venture debt at carrying value, less cash and cash equivalents (including Joint Venture share of cash), divided by the product of Adjusted EBITDA (including our share of Joint Venture EBITDA), multiplied by four. Adjusted EBITDA is a non-GAAP financial measure. For a definition and reconciliation of Adjusted EBITDA to its nearest GAAP equivalent and the calculation of the ratio, see the Appendix. 2) Pro forma for the stabilization of the three 100%-leased Northern Virginia developments acquired in June 2026. 13 5.2x 4.9x 3Q26 Reported Northern Virginia DC Acq. (Upon Stabilization) 3Q26 As Adjusted (0.3x) BBB+ / Baa1 (1) (2) |
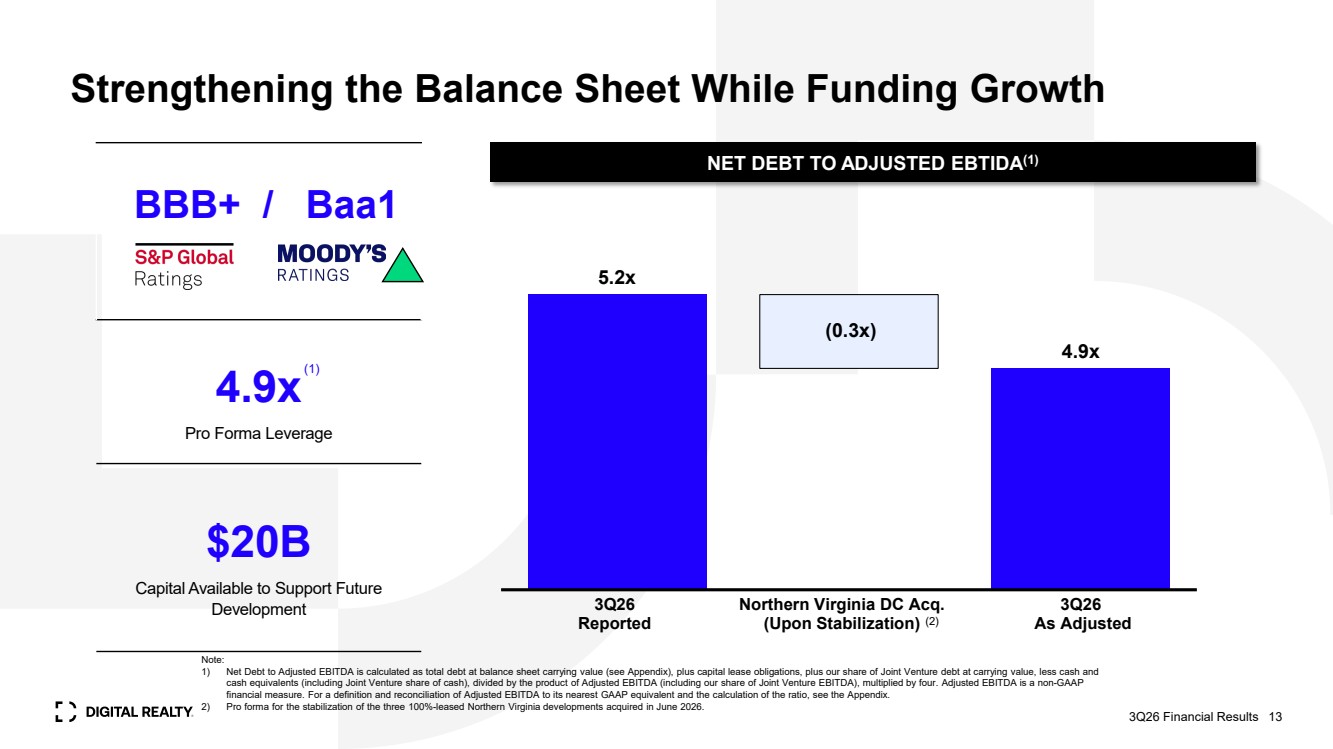
| $0.5 $1.9 $3.0 $4.0 $2.4 $1.8 $2.1 $1.9 $1.1 $3.1 2026 2027 2028 2029 2030 2031 2032 2033 2034 2035+ Unsecured Senior Notes - EUR Unsecured Senior Notes - USD Secured Mortgage Debt Pro Rata Share of JV Debt Unsecured Senior Notes - GBP Euro Term Loan Unsecured Senior Notes - CHF Other Unsecured Debt Unsecured Green Senior Notes - CHF Unsecured Green Senior Notes - EUR Unsecured Convertible Notes Unsecured Credit Facilities Pro Forma Payoffs Pro Forma Debt R € € Matching the Duration of Assets and Liabilities Modest Near-Term Maturities, Well-Laddered Debt Schedule DEBT MATURITY SCHEDULE AS OF SEPTEMBER 30, 2026 (1)(2) (U.S. $ in billions) DEBT PROFILE 3Q26 Financial Results (3) 4.6 YEARS Weighted Avg. Maturity (1)(2) 14 3.4% Weighted Avg. Coupon (1) ¥ $ $ € ¥ $ € R$ ¥ R$ ¥ $ R$ Note: As of September 30, 2026. 1) Includes Digital Realty’s pro rata share of unconsolidated entities’ loans and debt securities. Pro forma for the October issuance of the triple tranche 1.68%, 2.006% and 2.42% ₣510 million ($613 million) notes due 2029, 2032 and 2036, respectively, and 5.125% €1 billion ($1.12 billion) notes due 2036; assuming proceeds therefrom are used to pay down the unsecured credit facilities. 2) Assumes exercise of extension options. 3) Includes impact of cross-currency swaps. 92% Unsecured Unsecured Secured 80% Non-USD Euro USD GBP Other 89% Fixed Fixed Floating (3) |
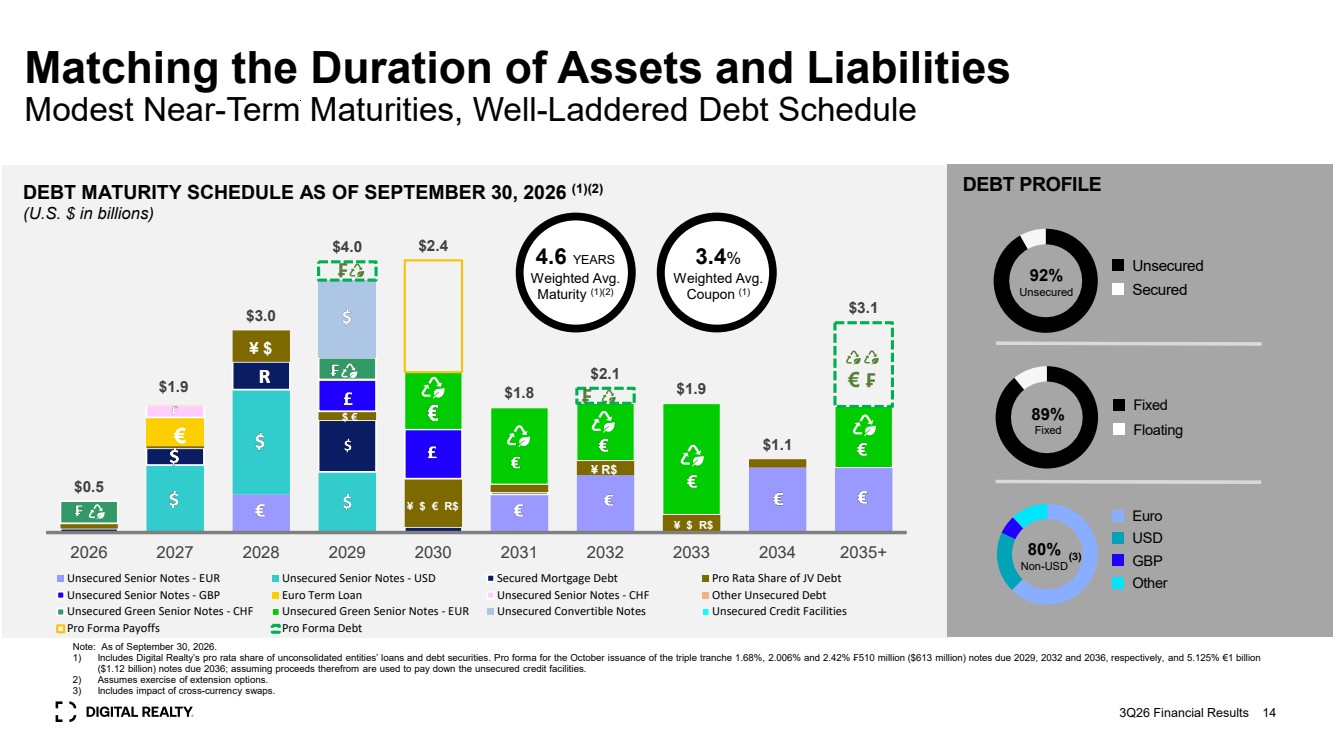
| 2026 Financial Guidance Update Improving Core Growth (1) (1) (2) 3Q26 Financial Results 15 As of February 5, 2026 As of April 23, 2026 As of July 23, 2026 As of October 29, 2026 Better/Worse Total Revenue (excluding promote income) $6,600 – $6,700 $6,650 - $6,750 $6,850 - $6,950 $7,050 - $7,125 Adjusted EBITDA $3,600 – $3,700 $3,650 - $3,750 $3,750 - $3,850 $3,800 - $3,850 Rental Rates on Renewal Leases (Cash) 6.0% – 8.0% 6.5% - 8.5% 9.0% - 11.0% 10.0% - 12.0% Year-End Portfolio Occupancy +50 – 100 bps +50 – 100 bps +75 – 125 bps +75 – 125 bps Same-Capital Cash NOI Growth 4.0% – 5.0% 4.0% – 5.0% 4.25 – 5.25% 5.25 – 5.75% Core FFO per Share (excluding net promote) $7.90 – $8.00 $8.00 – $8.10 $8.15 – $8.20 $8.30 – $8.35 CC Core FFO per Share (excluding net promote) $7.90 – $8.00 $7.95 – $8.05 $8.10 - $8.15 $8.25 - $8.30 Note: Dollars in millions except Core FFO per Share. The Company does not provide a reconciliation for non-GAAP estimates on a forward-looking basis, as it is unable to provide a meaningful or accurate calculation or estimation of reconciling items and the information is not available without unreasonable effort. This is due to the inherent difficulty of forecasting the timing and/or amount of various items that would impact net income attributable to common stockholders per diluted share, which is the most directly comparable forward-looking GAAP financial measure. This includes, for example, external growth factors, such as dispositions, and balance sheet items, such as debt issuances, that have not yet occurred, are out of the Company's control and/or cannot be reasonably predicted. For the same reasons, the Company is unable to address the probable significance of the unavailable information. Forward-looking non-GAAP financial measures provided without the most directly comparable GAAP financial measures may vary materially from the corresponding GAAP financial measures. 1) Adjusted EBITDA, Same-Capital Cash NOI Growth, Core FFO per Share (excluding net promote), and Constant-Currency Core FFO (excluding net promote) per Share are non-GAAP financial measures. For definitions and reconciliations of these measures to their nearest GAAP equivalents, see the Appendix. 2) Year-end portfolio occupancy guidance based on IT load (kW). 3) Presented on a constant currency basis. (1) (1)(3) |
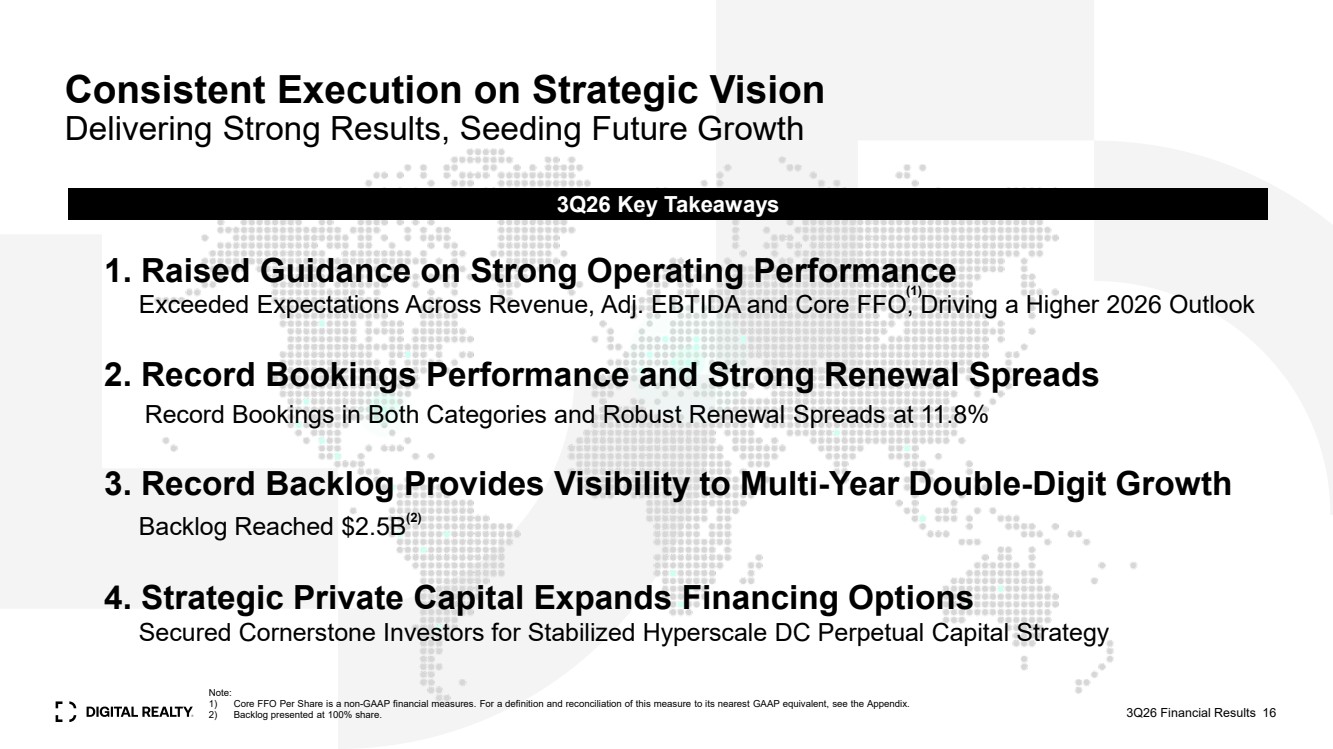
| Consistent Execution on Strategic Vision Delivering Strong Results, Seeding Future Growth 3Q26 Key Takeaways 3Q26 Financial Results 16 1. Raised Guidance on Strong Operating Performance Exceeded Expectations Across Revenue, Adj. EBTIDA and Core FFO, Driving a Higher 2026 Outlook 2. Record Bookings Performance and Strong Renewal Spreads 3. Record Backlog Provides Visibility to Multi-Year Double-Digit Growth Backlog Reached $2.5B 4. Strategic Private Capital Expands Financing Options Secured Cornerstone Investors for Stabilized Hyperscale DC Perpetual Capital Strategy Record Bookings in Both Categories and Robust Renewal Spreads at 11.8% (1) Note: 1) Core FFO Per Share is a non-GAAP financial measures. For a definition and reconciliation of this measure to its nearest GAAP equivalent, see the Appendix. 2) Backlog presented at 100% share. (2) |
| Appendix 3Q26 Financial Results 17 |
| Appendix Management Statements on Non-GAAP Measures 3Q26 Financial Results 18 The information included in this presentation contains certain non-GAAP financial measures that management believes are helpful in understanding our business, as further described below. Our definition and calculation of non-GAAP financial measures may differ from those of other REITs, and, therefore, may not be comparable. The non-GAAP financial measures should not be considered alternatives to net income or any other GAAP measurement of performance and should not be considered an alternative to cash flows from operating, investing or financing activities as a measure of liquidity. Funds From Operations (FFO): We calculate funds from operations, or FFO, in accordance with the standards established by the National Association of Real Estate Investment Trusts (Nareit) in the Nareit Funds From Operations White Paper - 2018 Restatement. FFO is a non-GAAP financial measure and represents net income (loss) available to common stockholders (computed in accordance with GAAP), excluding gain (loss) from the disposition of real estate assets, provision for impairment, real estate related depreciation and amortization (excluding amortization of deferred financing costs), our share of unconsolidated JV real estate related depreciation & amortization, net income attributable to noncontrolling interests in operating partnership and reconciling items related to noncontrolling interests. Management uses FFO as a supplemental performance measure because, in excluding real estate related depreciation and amortization and gains and losses from property dispositions and after adjustments for unconsolidated partnerships and joint ventures, it provides a performance measure that, when compared year over year, captures trends in occupancy rates, rental rates and operating costs. We also believe that, as a widely recognized measure of the performance of REITs, FFO will be used by investors as a basis to compare our operating performance with that of other REITs. However, because FFO excludes depreciation and amortization and captures neither the changes in the value of our data centers that result from use or market conditions, nor the level of capital expenditures and capitalized leasing commissions necessary to maintain the operating performance of our data centers, all of which have real economic effect and could materially impact our financial condition and results from operations, the utility of FFO as a measure of our performance is limited. Other REITs may not calculate FFO in accordance with the Nareit definition and, accordingly, our FFO may not be comparable to other REITs’ FFO. FFO should be considered only as a supplement to net income computed in accordance with GAAP as a measure of our performance. Core Funds from Operations (Core FFO) and Core FFO (excluding net promote): We present core funds from operations, or Core FFO, and Core FFO (excluding net promote) as supplemental operating measures because, in excluding certain items that do not reflect core revenue or expense streams, they provide a performance measure that, when compared year over year, capture trends in our core business operating performance. We calculate Core FFO by adding to or subtracting from FFO (i) other non-core revenue adjustments, (ii) transaction and integration expenses, (iii) gain (loss) on debt extinguishment and modifications, (iv) gain on / issuance costs associated with redeemed preferred stock, (v) severance, equity acceleration and legal expenses, (vi) gain/loss on FX and derivatives revaluation, and (vii) other non-core expense adjustments. We calculate Core FFO (excluding net promote) by adding to Core FFO the net impact of (i) promote income and (ii) promote expense (collectively “net promote”). Because certain of these adjustments have a real economic impact on our financial condition and results from operations, the utility of Core FFO and Core FFO (excluding net promote) as a measure of our performance is limited. Other REITs may calculate Core FFO and Core FFO (excluding net promote) differently than we do and accordingly, our Core FFO and Core FFO (excluding net promote) may not be comparable to other REITs’ Core FFO and Core FFO (excluding net promote). Core FFO and Core FFO (excluding net promote) should be considered only as a supplement to net income computed in accordance with GAAP as a measure of our performance. Adjusted Funds from Operations (AFFO): We present adjusted funds from operations, or AFFO, as a supplemental operating measure because, when compared year over year, it assesses our ability to fund dividend and distribution requirements from our operating activities. We also believe that, as a widely recognized measure of the operations of REITs, AFFO will be used by investors as a basis to assess our ability to fund dividend payments in comparison to other REITs, including on a per share and unit basis. We calculate AFFO by adding to or subtracting from Core FFO (i) non-real estate depreciation, (ii) amortization of deferred financing costs, (iii) amortization of debt discount/premium, (iv) non-cash stock-based compensation expense, (v) straight-line rental revenue, (vi) straight-line rental expense, (vii) above- and below-market rent amortization, (viii) deferred tax expense / (benefit), (ix) leasing compensation and internal lease commissions, and (x) recurring capital expenditures. Other REITs may calculate AFFO differently than we do and, accordingly, our AFFO may not be comparable to other REITs’ AFFO. AFFO should be considered only as a supplement to net income computed in accordance with GAAP as a measure of our performance. EBITDA and Adjusted EBITDA: We believe that earnings before interest expense, gain (loss) on debt extinguishment and modifications, income tax expense (benefit), and depreciation and amortization, or EBITDA, and Adjusted EBITDA (as defined below), are useful supplemental performance measures because they allow investors to view our performance without the impact of non-cash depreciation and amortization or the cost of debt and, with respect to Adjusted EBITDA, (i) unconsolidated entities real estate related depreciation & amortization, (ii) unconsolidated entities interest expense and tax expense, (iii) severance, equity acceleration and legal expenses, (iv) transaction and integration expenses, (v) gain (loss) on sale / deconsolidation, (vi) provision for impairment, (vii) other non-core adjustments, net, (viii) noncontrolling interests, (ix) preferred stock dividends, (x) gain on / issuance costs associated with redeemed preferred stock and (xi) net promote. In addition, we believe EBITDA and Adjusted EBITDA are frequently used by securities analysts, investors, and other interested parties in the evaluation of REITs. Because EBITDA and Adjusted EBITDA are calculated before recurring cash charges including interest expense and income taxes, exclude capitalized costs, such as leasing commissions, and are not adjusted for capital expenditures or other recurring cash requirements of our business, their utility as a measure of our performance is limited. Other REITs may calculate EBITDA and Adjusted EBITDA differently than we do and, accordingly, our EBITDA and Adjusted EBITDA may not be comparable to other REITs’ EBITDA and Adjusted EBITDA. Accordingly, EBITDA and Adjusted EBITDA should be considered only as supplements to net income computed in accordance with GAAP as a measure of our financial performance. Net Operating Income (NOI) and Cash NOI: Net operating income, or NOI, represents rental revenue, tenant reimbursement revenue and interconnection revenue less utilities expense, rental property operating expenses, property taxes and insurance expenses (as reflected in the statement of operations). NOI is commonly used by stockholders, company management and industry analysts as a measurement of operating performance of the company’s rental portfolio. Cash NOI is NOI less straight-line rents and above- and below-market rent amortization. Cash NOI is commonly used by stockholders, company management and industry analysts as a measure of property operating performance on a cash basis. Same-Capital Cash NOI represents data centers owned as of December 31, 2024 with less than 5% of total rentable square feet under development and excludes data centers that were undergoing, or were expected to undergo, development activities in 2025-2026, data centers classified as held for sale and contribution, and data centers sold or contributed to joint ventures for all periods presented (prior period numbers adjusted to reflect current same-capital pool). However, because NOI and cash NOI exclude depreciation and amortization and capture neither the changes in the value of our data centers that result from use or market conditions, nor the level of capital expenditures and capitalized leasing commissions necessary to maintain the operating performance of our data centers, all of which have real economic effect and could materially impact our results from operations, the utility of NOI and cash NOI as measures of our performance is limited. Other REITs may calculate NOI and cash NOI differently than we do and, accordingly, our NOI and cash NOI may not be comparable to other REITs’ NOI and cash NOI. NOI and cash NOI should be considered only as supplements to net income computed in accordance with GAAP as measures of our performance. |
| Appendix Forward-Looking Statements This information in this presentation contains forward-looking statements within the meaning of the federal securities laws, which are based on current expectations, forecasts and assumptions that involve risks and uncertainties that could cause actual outcomes and results to differ materially. Such forward-looking statements include statements relating to: our economic outlook; our expected investment and expansion activity; our joint ventures; the expected benefits and timing of PlatformDIGITAL®; the Data Gravity Index ; Data Gravity Index DGx ; public cloud services spending; the potential impact of artificial intelligence and data regulations; our sustainability initiatives; the expected effect of foreign currency translation adjustments on our financials; anticipated continued demand for our products and services; our liquidity; demand drivers and economic growth outlook; business drivers; our expected development plans and completions, including timing, total square footage, IT capacity and raised floor space upon completion; expected availability for leasing efforts and colocation initiatives; organizational initiatives; our product offerings; our connected data communities; joint venture opportunities; occupancy and total investment; our expected investment in our properties; our estimated time to stabilization and targeted returns at stabilization of our properties; our expected future acquisitions; acquisitions strategy; available inventory and development strategy; the signing and commencement of leases, and related rental revenue; lag between signing and commencement of leases; our backlog; future rents; our expected same store portfolio growth; our expected growth and stabilization of development completions and acquisitions; lease rollovers and expected rental rate changes; our re-leasing spreads; our expected yields on investments; our expectations with respect to capital investments at lease expiration on existing data center or colocation space; debt maturities; lease maturities; our other expected future financial and other results including guidance, and the assumptions underlying such results; our customers’ capital investments; our plans and intentions; future data center utilization, utilization rates, growth rates, trends, supply and demand; data center expansion plans; estimated kW/MW requirements; capital expenditures; the effect new leases and increases in rental rates will have on our rental revenues and results of operations; estimates of the value of our development portfolio; our ability to meet our liquidity needs, including the ability to raise additional capital; access to power; market forecasts; projected financial information and covenant metrics; Core FFO run rate and NOI growth; other forward looking financial data; leasing expectations; our exposure to tenants in certain industries; our expectations and underlying assumptions regarding our sensitivity to fluctuations in foreign exchange rates; and the sufficiency of our capital to fund future requirements. You can identify forward-looking statements by the use of forward-looking terminology such as “believes,” “expects,” “may,” “will,” “should,” “seeks,” “approximately,” “intends,” “plans,” “pro forma,” “estimates” or “anticipates” or the negative of these words and phrases or similar words or phrases which are predictions of or indicate future events or trends and discussions which do not relate solely to historical matters. Such statements are based on management’s beliefs and assumptions made based on information currently available to management. Such statements are subject to risks, uncertainties and assumptions and are not guarantees of future performance and may be affected by known and unknown risks, trends, uncertainties and factors that are beyond our control. Should one or more of these risks or uncertainties materialize, or should underlying assumptions prove incorrect, actual results may vary materially from those anticipated, estimated or projected. Some of the risks and uncertainties that may cause our actual results, performance or achievements to differ materially from those expressed or implied by forward-looking statements include, among others, the following: reduced demand for data centers or decreases in information technology spending; decreased rental rates, increased operating costs or increased vacancy rates; increased competition or available supply of data center capacity; the suitability of our data centers and data center infrastructure, delays or disruptions in connectivity or availability of power, or failures or breaches of our physical and information security infrastructure or services; breaches of our obligations or restrictions under our contracts with our customers; our inability to successfully develop and lease new properties and development capacity, and delays or unexpected costs in development of properties; the impact of current global and local economic, credit and market conditions; increased tariffs, global supply chain or procurement disruptions, or increased supply chain costs; the impact from periods of heightened inflation on our costs, such as operating and general and administrative expenses, interest expense and real estate acquisition and construction costs; the impact on our customers’ and our suppliers’ operations during an epidemic, pandemic, or other global events; our dependence upon significant customers, bankruptcy or insolvency of a major customer or a significant number of smaller customers, or defaults on or non-renewal of leases by customers; changes in political conditions, geopolitical turmoil, political instability, civil disturbances, restrictive governmental actions or nationalization in the countries in which we operate; our inability to retain data center capacity that we lease or sublease from third parties; information security, cyberattacks, security breaches, and data privacy breaches; difficulties managing an international business and acquiring or operating properties in foreign jurisdictions and unfamiliar metropolitan areas; our failure to realize the intended benefits from, or disruptions to our plans and operations or unknown or contingent liabilities related to, our recent and future acquisitions; our failure to successfully integrate and operate acquired or developed properties or businesses; difficulties in identifying properties to acquire and completing acquisitions; risks related to joint venture investments, including as a result of our lack of control of such investments; risks associated with using debt to fund our business activities, including re-financing and interest rate risks, our failure to repay debt when due, adverse changes in our credit ratings or our breach of covenants or other terms contained in our loan facilities and agreements; our failure to obtain necessary debt and equity financing, and our dependence on external sources of capital; financial market fluctuations and changes in foreign currency exchange rates; adverse economic or real estate developments in our industry or the industry sectors that we sell to, including risks relating to decreasing real estate valuations and impairment charges and goodwill and other intangible asset impairment charges; our inability to manage our growth effectively; losses in excess of our insurance coverage; our inability to attract and retain talent; environmental liabilities, risks related to natural disasters and our inability to achieve our sustainability goals; the expected operating performance of anticipated near-term acquisitions and descriptions relating to these expectations; our inability to comply with rules and regulations applicable to our company; Digital Realty Trust, Inc.’s failure to maintain its status as a REIT for U.S. federal income tax purposes; Digital Realty Trust, L.P.’s failure to qualify as a partnership for U.S. federal income tax purposes; restrictions on our ability to engage in certain business activities; and changes in local, state, federal and international laws and regulations, including related to taxation, real estate and zoning laws and increases in real property tax rates; the impact of any financial, accounting, legal or regulatory issues or litigation that may affect us. The risks included here are not exhaustive, and additional factors could adversely affect our business and financial performance. We discussed a number of additional material risks in our annual report on Form 10-K for the year ended December 31, 2025, and other filings with the Securities and Exchange Commission. Those risks continue to be relevant to our performance and financial condition. Moreover, we operate in a very competitive and rapidly changing environment. New risk factors emerge from time to time and it is not possible for management to predict all such risk factors, nor can it assess the impact of all such risk factors on the business or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statements. We expressly disclaim any responsibility to update forward-looking statements, whether as a result of new information, future events or otherwise. Digital Realty, Digital Realty Trust, the Digital Realty logo, Interxion, Turn-Key Flex, Powered Base Building, PlatformDIGITAL, Data Gravity Index, Data Gravity Index DGx, ServiceFabric, AnyScale Colo, and Pervasive Data Center Architecture (PDx),among others, are registered trademarks and service marks of Digital Realty Trust, Inc. in the United States and/or other countries. All other names, trademarks and service marks are the property of their respective owners. 3Q26 Financial Results 19 |
| Reconciliation of Non-GAAP Items To Their Closest GAAP Equivalent 3Q26 Financial Results 20 September 30, 2026 September 30, 2025 Net income available to common stockholders $ 185,165 $ 57,631 Adjustments: Noncontrolling interests in operating partnership 4,000 2,000 Real estate related depreciation and amortization (1) 527,646 487,182 Depreciation related to non-controlling interests (23,943) (22,888) Real estate related depreciation and amortization related to investment in unconsolidated entities 57,047 65,922 (Gain) loss on real estate transactions (8,403) (19,780) Provision for impairment - - FFO available to common stockholders and unitholders $ 741,512 $ 570,067 Basic FFO per share and unit $ 1.96 $ 1.64 Diluted FFO per share and unit $ 1.97 $ 1.65 Weighted average common stock and units outstanding Basic 378,331 347,301 Diluted 385,937 355,165 (1) Real estate related depreciation and amortization was computed as follows: Depreciation and amortization per income statement 539,471 497,002 Non-real estate depreciation (11,825) (9,820) $ 527,646 $ 487,182 September 30, 2026 September 30, 2025 FFO available to common stockholders and unitholders -- basic and diluted $ 741,512 $ 570,067 Weighted average common stock and units outstanding 378,331 347,301 Add: Effect of dilutive securities 439 399 Weighted average common stock and units outstanding -- diluted 378,770 347,700 Three Months Ended Digital Realty Trust, Inc. and Subsidiaries Reconciliation of Net Income Available to Common Stockholders to Funds From Operations (FFO) (in thousands, except per share and unit data) (unaudited) Three Months Ended |
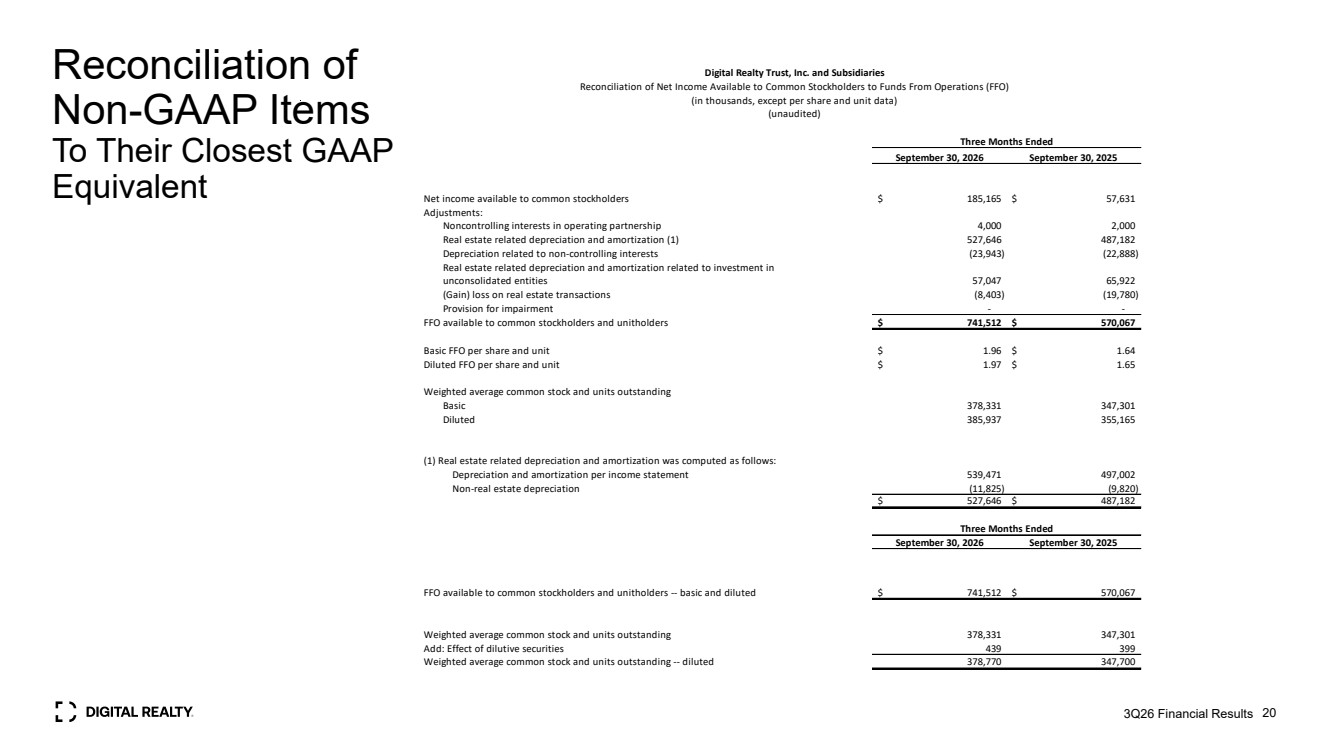
| Reconciliation of Non-GAAP Items To Their Closest GAAP Equivalent 3Q26 Financial Results 21 September 30, 2026 September 30, 2025 FFO available to common stockholders and unitholders -- diluted $ 741,512 $ 570,067 Other non-core revenue adjustments (3,219) (4,746) Transaction and integration expenses 48,961 86,559 Gain (loss) on debt extinguishment and modifications - - Severance, equity acceleration and legal expenses 2,643 1,794 (Gain) / Loss on FX and derivatives revaluation 7,515 252 Other non-core expense adjustments (2,149) 2,075 CFFO available to common stockholders and unitholders -- diluted $ 795,263 $ 656,001 Net promote - - Core Funds From Operations (excluding net promote) $ 795,263 $ 656,001 CFFO impact of holding '25 Exchange Rates Constant 1,693 - Constant Currency Core FFO (excluding net promote) $ 796,956 $ 656,001 Core FFO per share (excluding net promote) - diluted $ 2.10 $ 1.89 Constant Currency Core FFO Per Share (excluding net promote) $ 2.10 $ 1.89 Digital Realty Trust, Inc. and Subsidiaries Reconciliation of Funds From Operations (FFO) to Core Funds From Operations (CFFO) (in thousands, except per share and unit data) (unaudited) Three Months Ended |
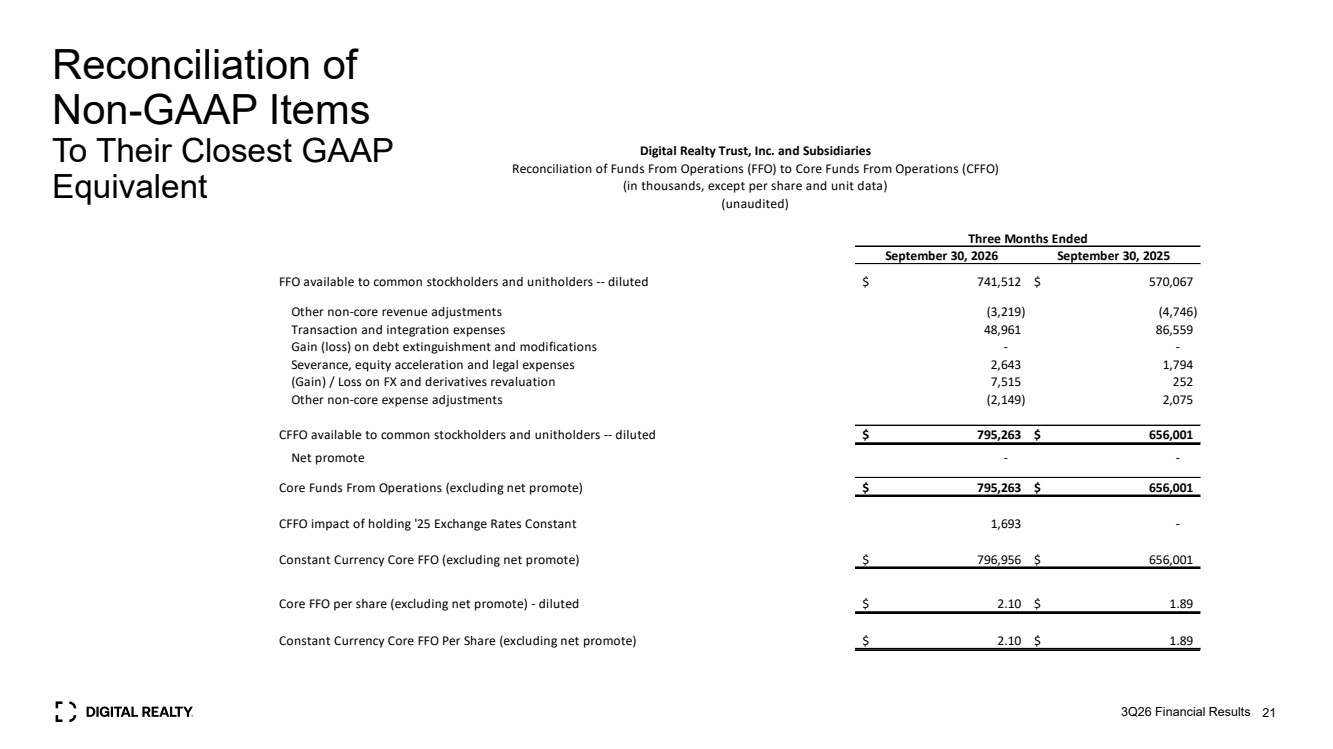
| Reconciliation of Non-GAAP Items To Their Closest GAAP Equivalent 3Q26 Financial Results 22 September 30, 2026 September 30, 2025 Net income available to common stockholders $ 185,165 $ 57,631 Interest expense 93,273 113,584 (Gain) loss on debt extinguishment and modifications - - Income tax expense (benefit) 8,751 11,695 Depreciation and amortization 539,471 497,002 EBITDA 826,660 679,912 Unconsolidated JV real estate related depreciation & amortization 57,047 65,922 Unconsolidated JV interest expense and tax expense 37,874 44,795 Severance, equity acceleration and legal expenses 2,643 1,794 Transaction and integration expenses 48,961 86,559 (Gain) loss on disposition of properties, net (8,403) (19,780) Provision for impairment - - Other non-core adjustments, net 4,474 2,523 Net promote - - Noncontrolling interests (1,735) (4,099) Preferred stock dividends 10,181 10,181 Adjusted EBITDA $ 977,702 $ 867,807 Digital Realty Trust, Inc. and Subsidiaries Reconciliation of Net Income Available to Common Stockholders to Earnings Before Interest, Taxes, Depreciation and Amortization (EBITDA) and Adjusted EBITDA (in thousands) (unaudited) Three Months Ended |
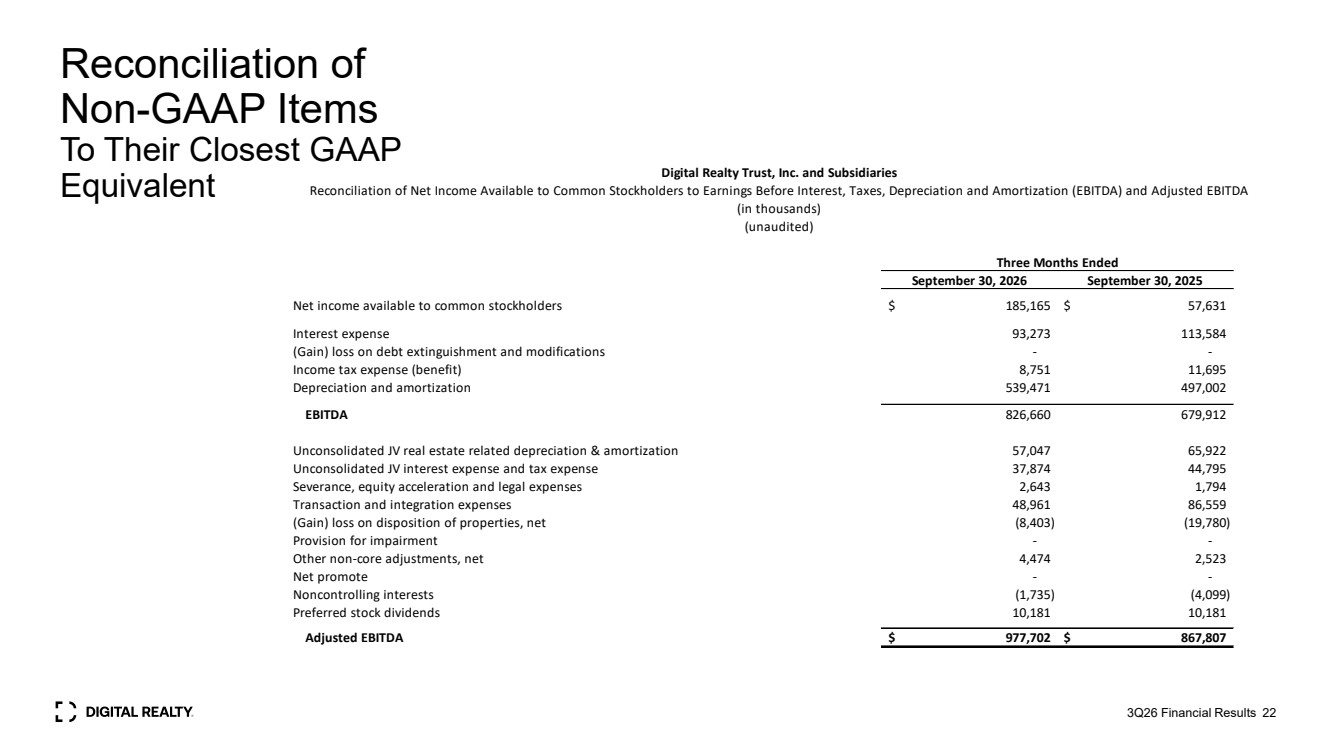
| Reconciliation of Non-GAAP Items To Their Closest GAAP Equivalent 3Q26 Financial Results 23 September 30, 2026 September 30, 2025 Rental revenues $ 879,053 $ 827,353 Tenant reimbursements - Utilities 321,395 275,237 Tenant reimbursements - Other 35,457 31,301 Interconnection and other 102,550 96,592 Total Revenue 1,338,455 1,230,483 Utilities 370,998 307,298 Rental property operating 222,124 215,454 Property taxes 46,905 44,373 Insurance 5,125 5,302 Total Expenses 645,152 572,427 Net Operating Income $ 693,303 $ 658,056 Less: Stabilized straight-line rent $ 5,443 $ 8,823 Above and below market rent 686 580 Same Capital Cash Net Operating Income $ 687,174 $ 648,653 Same Capital Cash NOI impact of holding '25 Exchange Rates Constant (181) - Constant Currency Same Capital Cash Net Operating Income $ 686,993 $ 648,653 September 30, 2026 September 30, 2025 Total operating revenues $ 1,902,418 $ 1,577,234 less: Proforma disposition adjustment 391 (407) plus: Constant currency adjustment 1,693 - Total operating revenues (as adjusted) $ 1,904,502 $ 1,576,827 Three Months Ended Three Months Ended Digital Realty Trust, Inc. and Subsidiaries Reconciliation of Same Capital Cash Net Operating Income (in thousands) (unaudited) |
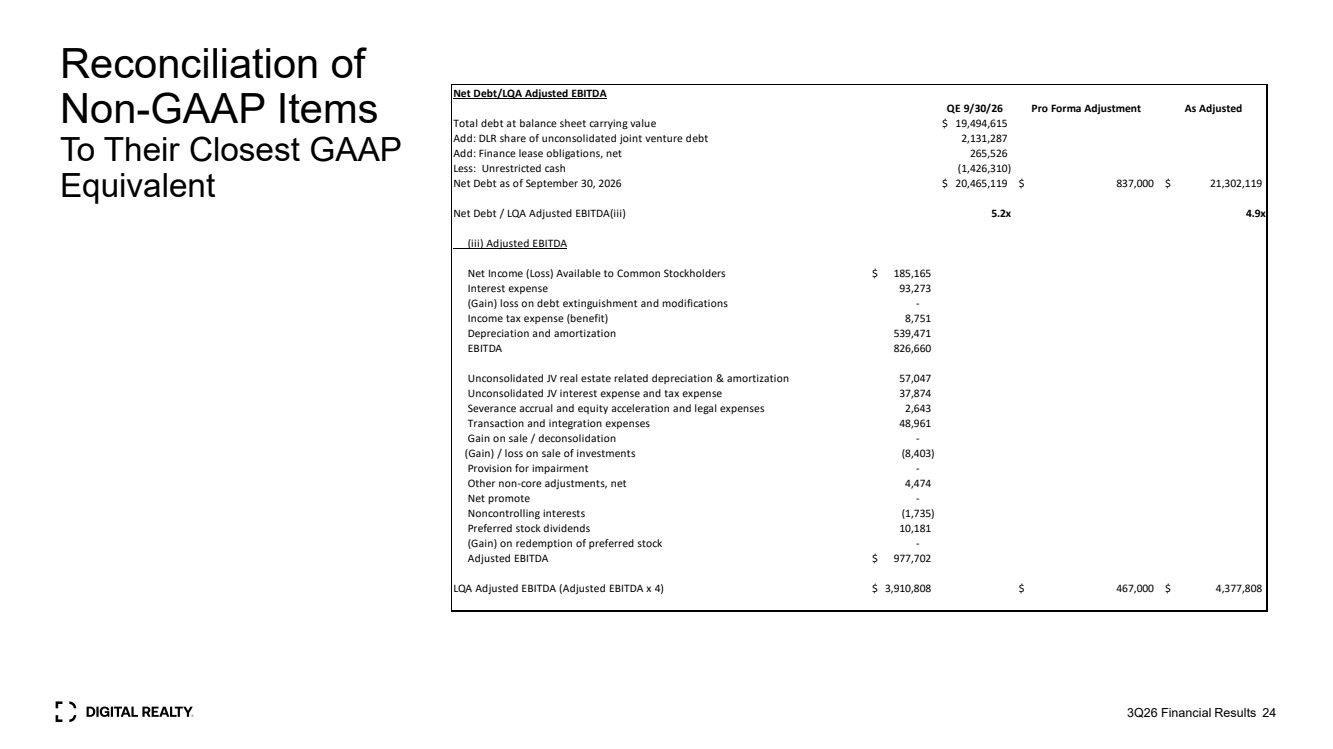
| Reconciliation of Non-GAAP Items To Their Closest GAAP Equivalent 3Q26 Financial Results 24 Net Debt/LQA Adjusted EBITDA QE 9/30/26 Pro Forma Adjustment As Adjusted Total debt at balance sheet carrying value $ 19,494,615 Add: DLR share of unconsolidated joint venture debt 2,131,287 Add: Finance lease obligations, net 265,526 Less: Unrestricted cash (1,426,310) Net Debt as of September 30, 2026 $ 20,465,119 $ 837,000 $ 21,302,119 Net Debt / LQA Adjusted EBITDA(iii) 5.2x 4.9x (iii) Adjusted EBITDA Net Income (Loss) Available to Common Stockholders $ 185,165 Interest expense 93,273 (Gain) loss on debt extinguishment and modifications - Income tax expense (benefit) 8,751 Depreciation and amortization 539,471 EBITDA 826,660 Unconsolidated JV real estate related depreciation & amortization 57,047 Unconsolidated JV interest expense and tax expense 37,874 Severance accrual and equity acceleration and legal expenses 2,643 Transaction and integration expenses 48,961 Gain on sale / deconsolidation - (Gain) / loss on sale of investments (8,403) Provision for impairment - Other non-core adjustments, net 4,474 Net promote - Noncontrolling interests (1,735) Preferred stock dividends 10,181 (Gain) on redemption of preferred stock - Adjusted EBITDA $ 977,702 LQA Adjusted EBITDA (Adjusted EBITDA x 4) $ 3,910,808 $ 467,000 $ 4,377,808 |
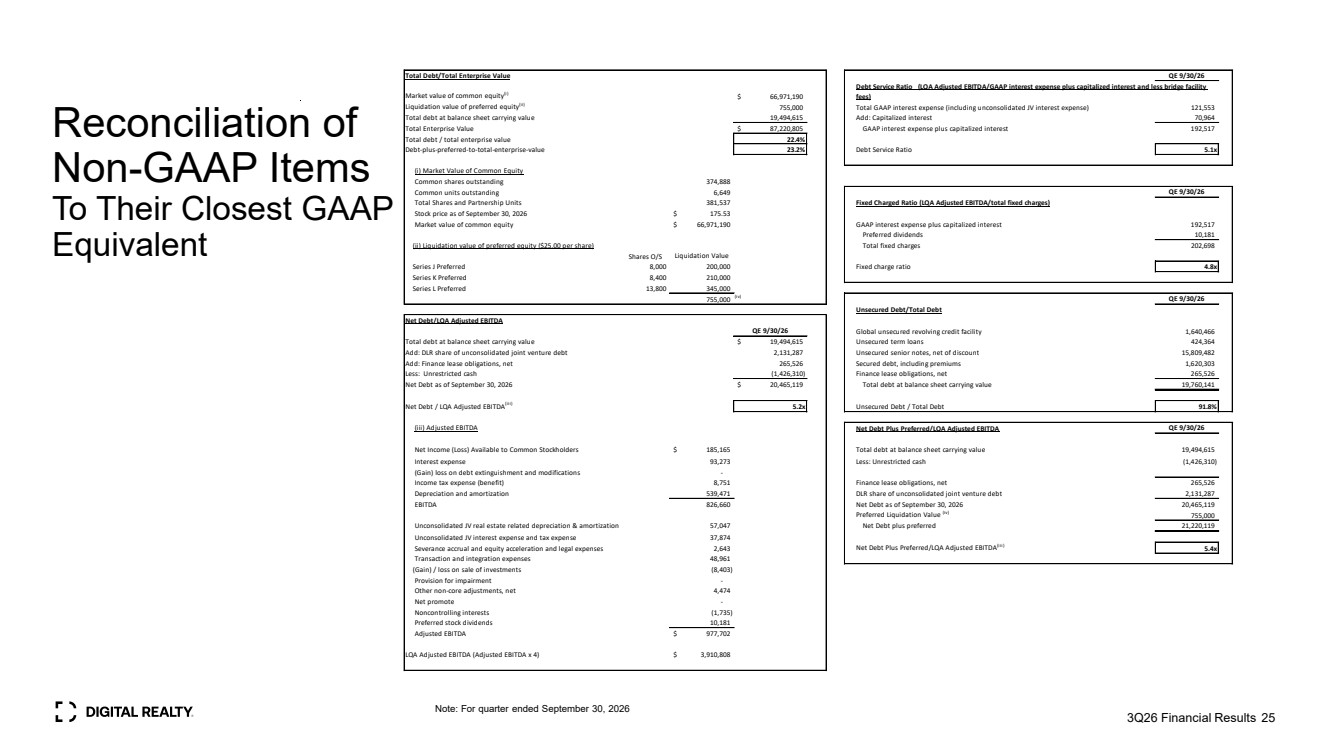
| Reconciliation of Non-GAAP Items To Their Closest GAAP Equivalent 3Q26 Financial Results 25 Note: For quarter ended September 30, 2026 Total Debt/Total Enterprise Value QE 9/30/26 Market value of common equity(i) $ 66,971,190 Liquidation value of preferred equity(ii) 755,000 Total GAAP interest expense (including unconsolidated JV interest expense) 121,553 Total debt at balance sheet carrying value 19,494,615 Add: Capitalized interest 70,964 Total Enterprise Value $ 87,220,805 GAAP interest expense plus capitalized interest 192,517 Total debt / total enterprise value 22.4% Debt-plus-preferred-to-total-enterprise-value 23.2% Debt Service Ratio 5.1x (i) Market Value of Common Equity Common shares outstanding 374,888 Common units outstanding 6,649 QE 9/30/26 Total Shares and Partnership Units 381,537 Fixed Charged Ratio (LQA Adjusted EBITDA/total fixed charges) Stock price as of September 30, 2026 $ 175.53 Market value of common equity $ 66,971,190 GAAP interest expense plus capitalized interest 192,517 Preferred dividends 10,181 (ii) Liquidation value of preferred equity ($25.00 per share) Total fixed charges 202,698 Shares O/S Liquidation Value Series J Preferred 8,000 200,000 Fixed charge ratio 4.8x Series K Preferred 8,400 210,000 Series L Preferred 13,800 345,000 755,000 (iv) QE 9/30/26 Unsecured Debt/Total Debt Net Debt/LQA Adjusted EBITDA QE 9/30/26 Global unsecured revolving credit facility 1,640,466 Total debt at balance sheet carrying value $ 19,494,615 Unsecured term loans 424,364 Add: DLR share of unconsolidated joint venture debt 2,131,287 Unsecured senior notes, net of discount 15,809,482 Add: Finance lease obligations, net 265,526 Secured debt, including premiums 1,620,303 Less: Unrestricted cash (1,426,310) Finance lease obligations, net 265,526 Net Debt as of September 30, 2026 $ 20,465,119 Total debt at balance sheet carrying value 19,760,141 Net Debt / LQA Adjusted EBITDA(iii) 5.2x Unsecured Debt / Total Debt 91.8% (iii) Adjusted EBITDA Net Debt Plus Preferred/LQA Adjusted EBITDA QE 9/30/26 Net Income (Loss) Available to Common Stockholders $ 185,165 Total debt at balance sheet carrying value 19,494,615 Interest expense 93,273 Less: Unrestricted cash (1,426,310) (Gain) loss on debt extinguishment and modifications - Income tax expense (benefit) 8,751 Finance lease obligations, net 265,526 Depreciation and amortization 539,471 DLR share of unconsolidated joint venture debt 2,131,287 EBITDA 826,660 Net Debt as of September 30, 2026 20,465,119 Preferred Liquidation Value (iv) 755,000 Unconsolidated JV real estate related depreciation & amortization 57,047 Net Debt plus preferred 21,220,119 Unconsolidated JV interest expense and tax expense 37,874 Severance accrual and equity acceleration and legal expenses 2,643 Net Debt Plus Preferred/LQA Adjusted EBITDA(iii) 5.4x Transaction and integration expenses 48,961 (Gain) / loss on sale of investments (8,403) Provision for impairment - Other non-core adjustments, net 4,474 Net promote - Noncontrolling interests (1,735) Preferred stock dividends 10,181 Adjusted EBITDA $ 977,702 LQA Adjusted EBITDA (Adjusted EBITDA x 4) $ 3,910,808 Debt Service Ratio (LQA Adjusted EBITDA/GAAP interest expense plus capitalized interest and less bridge facility fees) |
| Thank you |